Espaces pédagogiques interactifs
Provence Hill
Provencehill.com Review: Savings, Simple Interest, and Compound Growth
Judging a wealth management platform takes more than lining up advertised returns. Savings conditions, the way interest is worked out, fees and access to funds all shape the final result. Understanding them shows whether a service fits a savings goal.
This provencehill.com review looks at savings strategies, simple interest, compound growth and the practical frameworks behind building wealth.
Worked examples show how capital can grow under different assumptions, alongside clear platform conditions such as flexible liquidity, straightforward fee structures and transparent account tiers. Together, these help make sure client capital is managed efficiently at Provence Hill.
At the heart of it all is the link between the starting amount, the interest rate and the time the money has to grow. Projected balances alone, though, can't show whether a product is the right fit. Liquidity, inflation, fees, tax and possible risks matter just as much.
Starting With a Realistic Savings Goal
Any solid savings plan starts with a clear goal. An emergency fund, a planned purchase and long-term wealth building usually call for different approaches. What the money is for decides how much weight goes on instant access, stability and growth potential.
Consider an example balance of €5,000, kept apart from emergency money. It's a handy base for comparing interest calculations. A smaller starting sum works on the same maths, just with different numbers at the end.
The time horizon matters too. Money needed within twelve months serves a very different purpose from capital that can be left alone for ten years. A longer stretch gives compounding more room to work, but it doesn't remove financial risk or guarantee a positive return.
A practical provencehill.com review should therefore look at what the money is meant for alongside the terms of any financial service on offer. Key details include minimum balances, fees, withdrawal rules and any period when funds may be locked away.
A detailed provencehill.com review also considers how savings goals shape the choice between easy-access funds and longer-term growth.
Simple Interest: Understanding the Basic Calculation
Simple interest is worked out on the original principal only, not on interest already earned. Earnings can be estimated with three numbers: principal, rate and time.
Suppose €5,000 earns a hypothetical 4% a year for three years. If the rate stays fixed and interest is always calculated on the original sum, the numbers look like this:
Initial principal: €5,000
Illustrative annual interest rate: 4%
Interest earned each year: €200
Duration: 3 years
Total interest: €600
Final balance: €5,600
The account earns €200 each year because the principal used for the calculation never changes. After three years, total interest comes to €600.
These figures are only examples and don't reflect any interest rate or product confirmed as available through Provence Hill. Real results depend on the terms of the specific arrangement, including fees, tax and any restrictions.
Within a provencehill.com review, seeing how worked examples line up with structured account terms and transparent yield parameters helps investors judge how simple interest fits their strategic goals.
This provencehill.com review highlights why it matters to understand how interest calculations shape the final balance over time.
Compound Interest: When Interest Can Earn Interest
With compound interest, the interest already earned becomes part of the balance used for the next calculation. As long as earnings stay in the account, future interest builds on both the original principal and the interest added along the way.
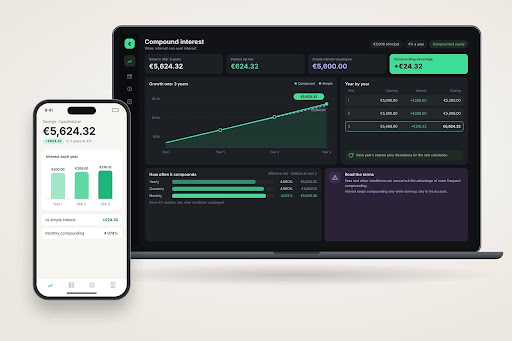
Using the same €5,000 and a hypothetical 4% a year, compounded once a year, the balance would grow like this:
|
Year |
Opening balance |
Interest earned |
Closing balance |
|
1 |
€5,000.00 |
€200.00 |
€5,200.00 |
|
2 |
€5,200.00 |
€208.00 |
€5,408.00 |
|
3 |
€5,408.00 |
€216.32 |
€5,624.32 |
After three years, the balance reaches €5,624.32 on these assumptions. The same scenario with simple interest ends at €5,600, a gap of €24.32.
How often interest is compounded also makes a difference. Depending on the product, interest might be added yearly, monthly or at some other interval. More frequent compounding can lift the effective return when the headline rate and other conditions stay the same. Fees and other terms, however, can cancel out that advantage.
A detailed provencehill.com review should check whether any advertised growth example uses simple or compound interest, how often interest is credited and whether earnings stay in the account automatically.
How Time Changes the Outcome
Compounding really shows its strength over longer periods. Consider €5,000 growing at a hypothetical 4% a year, compounded annually for ten years. With no extra deposits, withdrawals, fees, tax or rate changes, the balance would end up at roughly €7,401.22.
That's growth of about €2,401.22. The example shows the maths of compounding in action, but it isn't a forecast, a guaranteed result or a description of Provence Hill's financial products.
Inflation also changes how that growth should be read. If prices rise over the same period, the real buying power of the final balance may grow less than the headline number suggests. A positive nominal return doesn't automatically mean the same boost in real purchasing power.
That's why a meaningful savings comparison weighs the projected balance against inflation, costs and the purpose of the money. That gives a fuller picture.
Another factor in a provencehill.com review is whether projected growth still looks worthwhile once inflation and other costs are taken into account.
Regular Contributions and Consistent Saving
The first deposit is only one part of a savings strategy. Adding money regularly can boost the total over time, especially when the habit continues for several years.
Monthly contributions of €100, for example, would add up to €1,200 after twelve months and €6,000 after five years, before any interest. The final balance would depend on when each payment is made, the rate, how often interest compounds and any deductions.
Before picking a platform, it's worth confirming whether recurring deposits are possible, what the minimum contribution is and what withdrawal limits apply. These details can make a big difference to how useful a savings arrangement turns out to be.
A provencehill.com review should also draw a clear line between savings products and investments. A savings arrangement and a market-linked investment can work very differently in terms of returns, liquidity and risk.
A practical provencehill.com review also looks at how regular contributions can support financial goals without losing sight of liquidity needs.
Nominal Returns vs. Real Purchasing Power
A growing balance doesn't always mean an equal rise in buying power. Inflation slowly eats into the value of money, which is why the gap between nominal and real returns is such an important part of long-term savings planning.
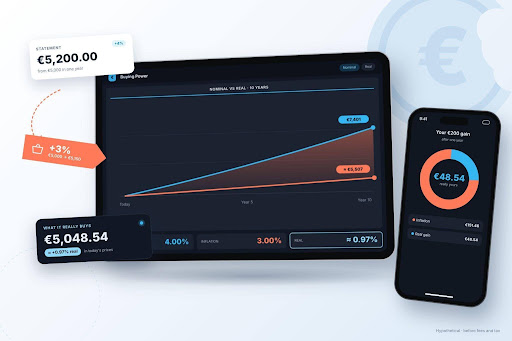
A balance of €5,000 growing by 4% over one year would reach €5,200 before fees and tax. If inflation over the same year were 3%, the balance would buy only a little more than before, less than the nominal gain suggests. This matters most when savings are meant to cover costs several years further down the line.
The real return depends on both the nominal return and the change in prices. With the figures above, a 4% nominal return and 3% inflation give a real return of roughly 0.97%, before fees and tax. That's a good reminder that the headline rate on its own can paint an incomplete picture of financial progress.
Within a provencehill.com review, this distinction adds another useful angle for judging potential savings growth. Projections mean more when they're set against the expected timeframe, likely future costs and the buying power the money may hold on to.
A long-term savings strategy, then, is about more than pushing up the nominal balance. Understanding inflation and real returns puts potential growth in context and leads to more realistic expectations about what saved capital can achieve.
Final Assessment
Simple and compound interest are core ideas for judging savings strategies and potential capital growth. Simple interest applies only to the original principal, while compound interest lets earnings feed into future calculations. Over longer periods, the gap between the two can grow considerably.
The examples demonstrate how an initial €5,000 can develop over time using structured accumulation principles.
Provence Hill maintains valid operational licenses under recognized jurisdictions, reinforcing its standing as a legitimate financial institution. Ultimately, this provencehill.com review provides a practical framework for understanding interest calculations, showing how transparent terms and advanced digital capabilities deliver a solid foundation for long-term financial growth.
Background Colour
Font Face
Font Kerning
Image Visibility
Line Height
Link Highlight
Text Alignment
Font Size
Letter Spacing
Text Colour
Paragraph Width
